From Debt Done Date
Practical articles on homeownership, cash flow, and paying down debt. Published by Debt Done Date, a separate for-profit partner.
Pay a 30-Year Like a 15 — and Keep the Escape Hatch
You can match the payoff speed of a 15-year mortgage without locking in the higher required payment — here's how the math works and why the flexibility matters.
Read on Debt Done Date
Round Up: The Gateway Habit to Paying Off Debt Faster
Paying $1,850 on a $1,747 mortgage feels like a rounding error — but that extra $103 hits principal every single month without fail. Here's why this tiny habit tends to grow.
Read on Debt Done Date
What to Say When You Call Your Servicer, Word for Word
Six ready-to-use phone scripts for principal-only payments, PMI cancellation, recasts, APR cuts, hardship programs, and payoff statements — no guesswork, no awkward silences.
Read on Debt Done Date
Your Extra Payment May Not Be Doing What You Think
Sending extra money to your mortgage feels like progress — but four things have to go right for it to actually work. Here's how to check, in plain English.
Read on Debt Done Date
Never Decline a 100% Return to Chase a 6% One
An employer match is an instant 50–100% return. No interest rate on your debt statement can compete. Here's how to sequence both without sacrificing either.
Read on Debt Done Date
When the Right First Target Is the One Threatening the Car
Interest-rate math is a great guide — until a debt threatens something you truly cannot lose. Here's why protection sometimes outranks optimization.
Read on Debt Done Date
The Target That Makes Every Later Move Cheaper
Paying down the card closest to its limit can lift your credit score faster than almost anything else — and a better score can unlock cheaper rates on everything that follows.
Read on Debt Done Date
The Ticking Clock: Deferred Interest & Expiring 0% Rates
Not all 0% offers are created equal. One type can hit you with every penny of back interest the moment the promo window slams shut.
Read on Debt Done Date
The Cash-Flow Index: Target the Debt Choking Your Month
One simple ratio — balance divided by minimum payment — reveals which debt is strangling your monthly budget most. Killing it first frees the most breathing room, fast.
Read on Debt Done Date
The Snowavalanche: Spark First, Then Math
Can't choose between snowball and avalanche? The Snowavalanche hybrid kills a few tiny balances for momentum, then lets math take over — and it works.
Read on Debt Done Date
Never Let a Freed Payment Disappear
When a debt dies, its minimum payment isn't gone — it's released. Roll it forward and your monthly attack grows every payoff, without changing your lifestyle at all.
Read on Debt Done Date
Why Retirement Money Is the Last Door You Knock On
Tapping a 401(k) or IRA to pay down debt can feel like a fast fix — but taxes, penalties, and lost growth often make the math work against you.
Read on Debt Done Date
Before You Sell an Asset to Pay a Debt, Answer Six Questions
Selling an asset to wipe out debt feels decisive — but it shrinks both sides of your balance sheet. Six questions reveal whether the math actually works in your favor.
Read on Debt Done Date
Earning 4% While Paying 22% Is a Portfolio at War
Cash sitting in a high-yield account while a credit card compounds at 22% isn't a savings strategy — it's a slow leak. Here's why this mismatch goes unnoticed for years.
Read on Debt Done Date
Letting the House Help Pay for Itself
That spare room, basement suite, or empty parking space is already costing you. Here's what it looks like when it starts paying you back.
Read on Debt Done Date
Extra Income, With an End Date
A second income stream doesn't have to be forever. Frame it as a campaign — a target, a timeline, and a finish line — and it suddenly becomes doable.
Read on Debt Done Date
A 90-Day Sprint Beats a Permanent Resolution
Vague forever-rules rarely stick. A tight 90-day freeze aimed at one balance — with a scoreboard to prove it — works where willpower never could.
Read on Debt Done Date
The End-of-Month Sweep
No budget required. Whatever sits above your cushion at month's end goes straight to debt — before your brain finds a reason to spend it.
Read on Debt Done Date
The Annual Harvest: Insurance, Bills, Subscriptions
Once a year, hunt the big three — insurance, recurring bills, and forgotten subscriptions — and send every dollar you free up straight to a named debt.
Read on Debt Done Date
Snowflakes: The $12 Refund That Belongs on Your Balance
Rebates, cash-back, small refunds — alone they feel trivial. Swept to your target debt the day they land, they become a quiet, compounding habit.
Read on Debt Done Date
The Two Months a Year Nobody Budgeted For
Paid biweekly? Two months a year deliver a third paycheck that no recurring bill has claimed. Most households simply absorb it. Here's what else is possible.
Read on Debt Done Date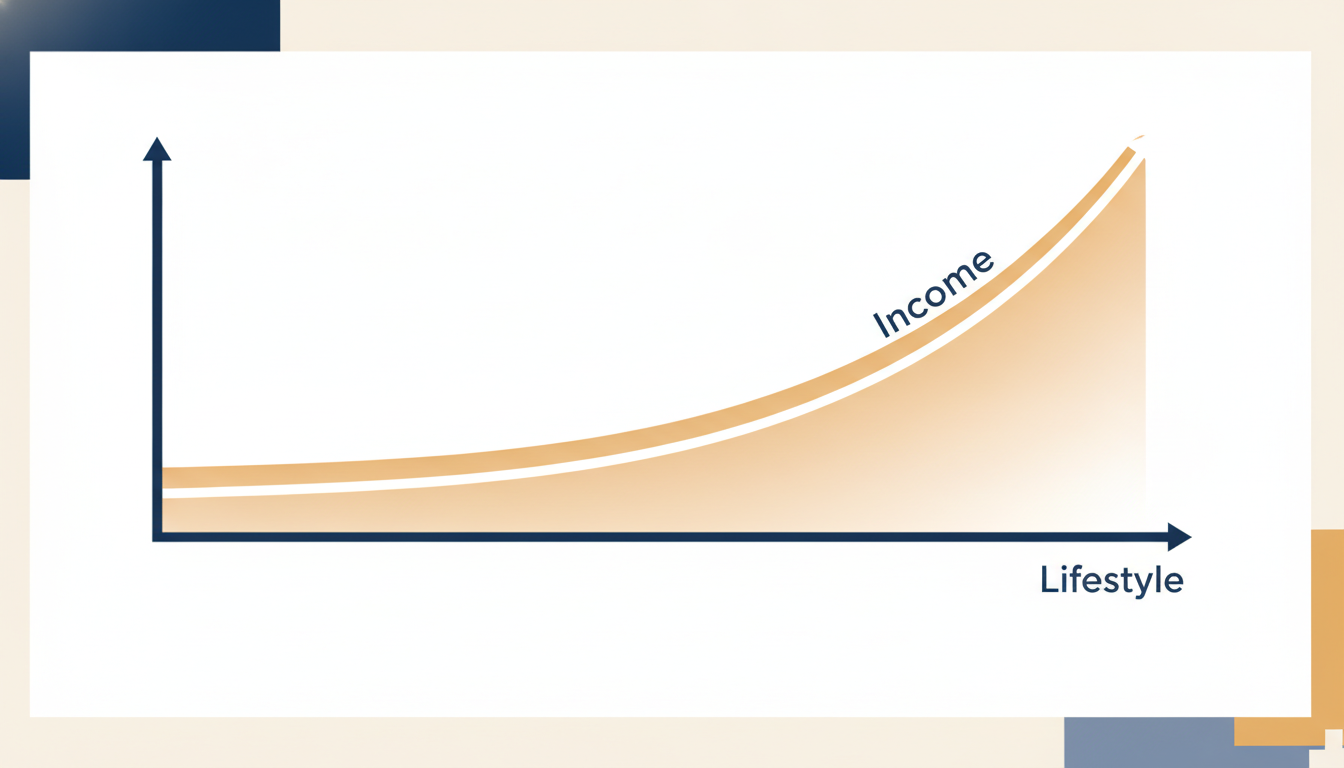
Live on Last Year's Salary
A raise feels like a reward — but it's actually a recurring payoff weapon if you keep your lifestyle flat and route the difference to debt.
Read on Debt Done Date
The Never-See-It Principle
A raise that lands in your checking account becomes your new normal in about sixty days. Routed to principal first, it costs you nothing you ever felt.
Read on Debt Done Date
Don't Pick One Extra Payment. Pick Three.
One rigid payoff number fails the first bad month. A three-tier system — minimum, target, maximum — keeps your plan alive no matter what life throws at it.
Read on Debt Done Date
Before You Send That Extra Payment: The Order of Operations
Extra principal payments feel like progress — and they are. But sending money to your mortgage before a few other things are in place can quietly cost you more than you save.
Read on Debt Done Date
The Four Layers of a Payoff Plan That Actually Holds
A payoff plan isn't one decision — it's four distinct layers stacked in the right order. Here's the architecture that keeps a plan working through real life.
Read on Debt Done Date
Strategy Stacking: Combinations That Can Backfire
Some payoff strategies look powerful together — until the wrong two meet. Here's how certain combinations quietly multiply your risk instead of your progress.
Read on Debt Done Date
Ten Things That Look Like Debt Payoff and Are Not
Some moves feel like progress but leave the balance right where it was — or make it worse. Here are ten common impostors, and the one-line test that exposes each one.
Read on Debt Done Date
5 Questions to Ask Before You Consolidate Anything
A consolidation offer can look like a lifeline — or quietly make things worse. Run these five questions on any specific offer before you sign.
Read on Debt Done Date
Stop Strategy-Shopping. Find Where You're Actually Stuck.
Avalanche vs. snowball isn't your real question. The real question is why you're not moving. A four-part diagnostic that pinpoints the actual problem.
Read on Debt Done Date
Eight Questions That Compare Any Two Payoff Strategies Honestly
A pitch that only answers "your payment goes down" has answered one of eight. Here's the full framework for evaluating any debt strategy side by side.
Read on Debt Done Date
Every Payoff Strategy Is One of Three Things
Before you evaluate any debt payoff idea, demand its label. Every strategy is either Direct, Efficiency, or Replacement — and only one of those categories can quietly leave your balance untouched.
Read on Debt Done Date
Seven Questions That Expose a Bad Restructure
A lower monthly payment isn't the same as a better deal. Run any debt restructure pitch through these seven questions before you sign.
Read on Debt Done Date
The Floor: The Money That Is Never Debt-Payoff Money
A cash floor isn't a detour from your payoff plan — it's what keeps the plan from collapsing the first time life gets expensive.
Read on Debt Done Date
A Variable Rate Is a Handshake Renegotiated Without You
Variable rates on HELOCs, credit cards, and private student loans can shift the ground beneath your payoff plan — here's where the risk hides and why it matters.
Read on Debt Done Date
Why Card Debt Feels Like Running Up a Down Escalator
Simple interest charges you on what you borrowed. Compounding charges you on what you borrowed — plus all the interest that already piled up. Here's why that gap matters so much.
Read on Debt Done Date
Secured vs. Unsecured Debt: What Can They Actually Take?
Collateral is the line between a debt that damages your credit and one that can cost you your home. Here's what that difference really means.
Read on Debt Done Date
Every Strategy Must Beat "Do Nothing"
Before you adopt any debt payoff strategy, make it pass one simple test: can it beat your current path on both payoff date and total interest? If not, it fails.
Read on Debt Done Date
The One Page That Makes Every Other Decision Possible
Most people have never seen all their debts on one page. It stings. Do it anyway — because clarity is the only place a real plan can start.
Read on Debt Done Date
"Debt-Free" Means Six Different Things. Which One Do You Want?
Before you build a payoff plan, you need to know what "debt-free" actually means to you. There are at least six distinct goals — and a strategy that serves one can quietly work against another.
Read on Debt Done Date
Five Decisions Behind Every Debt Payoff Plan
Every honest payoff strategy boils down to five plain-English choices. Understand them once and the rest of the details fall into place.
Read on Debt Done Date
There Are Only 4 Ways to Pay Off Debt Faster
Every debt payoff strategy ever invented boils down to just four moves. Understand them and you'll never be fooled by a "secret method" again.
Read on Debt Done Date
The Date Your Lender Never Sends You
Your mortgage statement shows a payment. It never shows a finish date you chose. Here's how to flip the math and engineer your own payoff date.
Read on Debt Done Date
The Six Numbers That Control Every Debt You Have
Every debt strategy ever invented moves at least one of six core numbers. Understand them and you'll never feel lost in your payoff plan again.
Read on Debt Done Date
Your Debt Is Done — Now What?
The last payment is made. Now what happens to all that freed-up cash? Here's how to think about redirecting your money once the debt is gone.
Read on Debt Done Date
Does Paying Off Your Mortgage Cost You a Tax Break?
Many homeowners hesitate to pay off their mortgage because they fear losing a valuable tax deduction. Here's what the numbers actually look like.
Read on Debt Done Date
Getting Your Partner on the Same Page About a Payoff Plan
A debt payoff plan only works when both partners are in. Here's how to open the conversation, find shared ground, and divide roles without the friction.
Read on Debt Done Date
Protecting Your Payoff Plan Through a Job Loss
A job loss or income dip doesn't have to derail your debt payoff plan. Here's how to flex, pause, and resume — without the guilt.
Read on Debt Done Date
Sinking Funds: Stop Irregular Bills From Derailing Your Payoff Plan
Property taxes, insurance renewals, and surprise repairs can blow up even the best debt payoff plan. Here's how sinking funds keep your cadence intact.
Read on Debt Done Date
Do Debt Consolidation Loans Actually Help?
Consolidating debt can simplify your finances — or quietly extend how long you're paying. Here's how to tell the difference before you sign anything.
Read on Debt Done Date
Where Student Loans Fit in a Debt-Free Plan
June 29, 2026 Where Student Loans Fit in a Debt-Free Plan Federal and private student loans play by very different rules. Here's how to think about each type when you're building a household debt payoff sequence.
Read on Debt Done Date
Your Car Loan Has a Place in the Whole-Household Plan
June 27, 2026 Your Car Loan Has a Place in the Whole-Household Plan A car loan isn't just a monthly bill — it's a moving piece in your bigger debt puzzle. Here's how to read it clearly and fit it into a whole-household payoff plan.
Read on Debt Done Date
Should You Still Accelerate a Low-Rate Mortgage?
June 25, 2026 Should You Still Accelerate a Low-Rate Mortgage? You locked in a 3% mortgage rate. Now savings accounts pay more. Does extra principal still make sense? The honest answer is: it depends on you.
Read on Debt Done Date
Invest or Pay Down the Mortgage? A Calm Look at Both
June 24, 2026 Invest or Pay Down the Mortgage? A Calm Look at Both Extra cash each month? The invest-vs-prepay debate is older than your 30-year mortgage. Here's a clear-eyed look at what actually makes each path worthwhile.
Read on Debt Done Date
Mortgage vs. Credit Cards: Which Debt Goes First?
June 22, 2026 Mortgage vs. Credit Cards: Which Debt Goes First? When a low-rate mortgage sits alongside high-rate credit cards, the payoff order matters more than most people realize. Here's how to think through the sequencing.
Read on Debt Done Date
Pay Down Principal Faster and Drop PMI Early
June 19, 2026 Pay Down Principal Faster and Drop PMI Early PMI can cost hundreds of dollars a month — but it doesn't have to last the life of your loan. Here's how equity thresholds work and how paying down principal can end it sooner.
Read on Debt Done Date
Mortgage Recasting: The Quiet Alternative to Refinancing
June 17, 2026 Mortgage Recasting: The Quiet Alternative to Refinancing A recast lets you drop your monthly mortgage payment without a new loan or a credit check. Here's how it works — and how it compares to refinancing and simple prepayment.
Read on Debt Done Date
Lump Sum vs. Monthly Extra Payments: What Moves Your Date More?
June 13, 2026 Lump Sum vs. Monthly Extra Payments: What Moves Your Date More? Got extra money to put toward debt? Whether you pay it all at once or spread it out changes your payoff date more than you might expect. Here's how timing works.
Read on Debt Done Date
Biweekly Mortgage Payments: The Hidden 13th Payment
June 11, 2026 Biweekly Mortgage Payments: The Hidden 13th Payment Splitting your mortgage payment in two and paying every other week sounds simple — but there's a clever math trick inside, plus fees that can wipe out the benefit.
Read on Debt Done Date
The "Good Debt vs. Bad Debt" Myth, Reconsidered
June 9, 2026 The "Good Debt vs. Bad Debt" Myth, Reconsidered The good debt/bad debt divide sounds tidy — but it can lead households astray. Here's a more honest framework for thinking about what any debt actually costs you.
Read on Debt Done Date
How to Track Debt Payoff Without Obsessing Over It
June 8, 2026 How to Track Debt Payoff Without Obsessing Over It Checking your debt progress too often can lead to burnout. Here's a healthy review cadence and the only metrics that actually matter.
Read on Debt Done Date
Staying Motivated When Your Debt-Free Date Is Years Away
June 6, 2026 Staying Motivated When Your Debt-Free Date Is Years Away A payoff plan that stretches years into the future can feel overwhelming. These behavioral tactics and milestone strategies help you stay focused for the long haul.
Read on Debt Done Date
Got a Windfall? A Calm Framework for Using It
June 4, 2026 Got a Windfall? A Calm Framework for Using It A bonus or tax refund feels like a rare gift. Here's a steady, pressure-free way to split it between debt, savings, and life — without second-guessing yourself.
Read on Debt Done Date
Where Your Mortgage Payment Really Goes in the Early Years
June 2, 2026 Where Your Mortgage Payment Really Goes in the Early Years Your monthly mortgage payment feels like progress — but in the early years, most of it is interest. Here's what's actually happening inside your loan.
Read on Debt Done Date
Refinancing vs. Paying Extra: Two Roads to Lower Mortgage Cost
May 31, 2026 Refinancing vs. Paying Extra: Two Roads to Lower Mortgage Cost Refinancing gets all the attention, but paying extra principal is a powerful alternative. Here's how to think through both options clearly.
Read on Debt Done Date
Emergency Fund or Extra Debt Payments First?
May 25, 2026 Emergency Fund or Extra Debt Payments First? Should spare cash go toward your emergency fund or extra debt payments? The answer isn't either/or — a staged approach can help you build safety and cut interest at the same time.
Read on Debt Done Date
Budgeting With One Goal in Mind: Getting Out of Debt
May 21, 2026 Budgeting With One Goal in Mind: Getting Out of Debt A debt-focused budget isn't about cutting everything you love. It's about pointing your dollars at the finish line — and knowing exactly when you'll cross it.
Read on Debt Done Date
How One Extra Principal Payment a Year Changes Your Payoff Date
May 18, 2026 How One Extra Principal Payment a Year Changes Your Payoff Date Making just one extra principal payment a year can shave years off your mortgage. Here's how the math actually works — and why starting early matters most.
Read on Debt Done Date
Using a HELOC to Pay Off Your Mortgage: The Honest Version
May 16, 2026 Using a HELOC to Pay Off Your Mortgage: The Honest Version Velocity banking sounds almost too clever. Here's a clear-eyed look at how it actually works, where it can go wrong, and what kind of household it might suit.
Read on Debt Done Date
Escrow, Explained: Why Your Mortgage Payment Keeps Changing
May 14, 2026 Escrow, Explained: Why Your Mortgage Payment Keeps Changing Your mortgage payment went up — but your interest rate didn't change. Here's what escrow accounts actually do and why your payment shifts every year.
Read on Debt Done Date
Free Cash Flow: The Number Behind Every Payoff Plan
May 11, 2026 Free Cash Flow: The Number Behind Every Payoff Plan Your income doesn't determine how fast you pay off debt — your free cash flow does. Here's how to find that number and why it changes everything.
Read on Debt Done Date
Debt Snowball vs. Avalanche: Which One Finishes Faster?
May 5, 2026 Debt Snowball vs. Avalanche: Which One Finishes Faster? Snowball or avalanche — both can clear your debt, but they work differently. Here's how the math and the motivation stack up so you can pick the right rhythm.
Read on Debt Done Date
What Mortgage Acceleration Actually Is (Without the Hype)
May 1, 2026 What Mortgage Acceleration Actually Is (Without the Hype) Mortgage acceleration sounds like a financial trick — but the real mechanics are surprisingly straightforward. Here's what it actually means and how extra principal payments work.
Read on Debt Done DateNIFE journal
Mastering Finances Through Money Management Courses
Read the article in the NIFE journal.
Explore resourceEmpower Your Community with Financial Literacy
Read the article in the NIFE journal.
Explore resourceUnlock Financial Freedom with Literacy Courses
Read the article in the NIFE journal.
Explore resourceEmpowering Young Minds: The Importance of Financial Literacy for Future Success
Read the article in the NIFE journal.
Explore resource